November 8th, 2026
Bitcoin And: The Week That Was | November 2–6, 2026 | Episodes 1420–1423
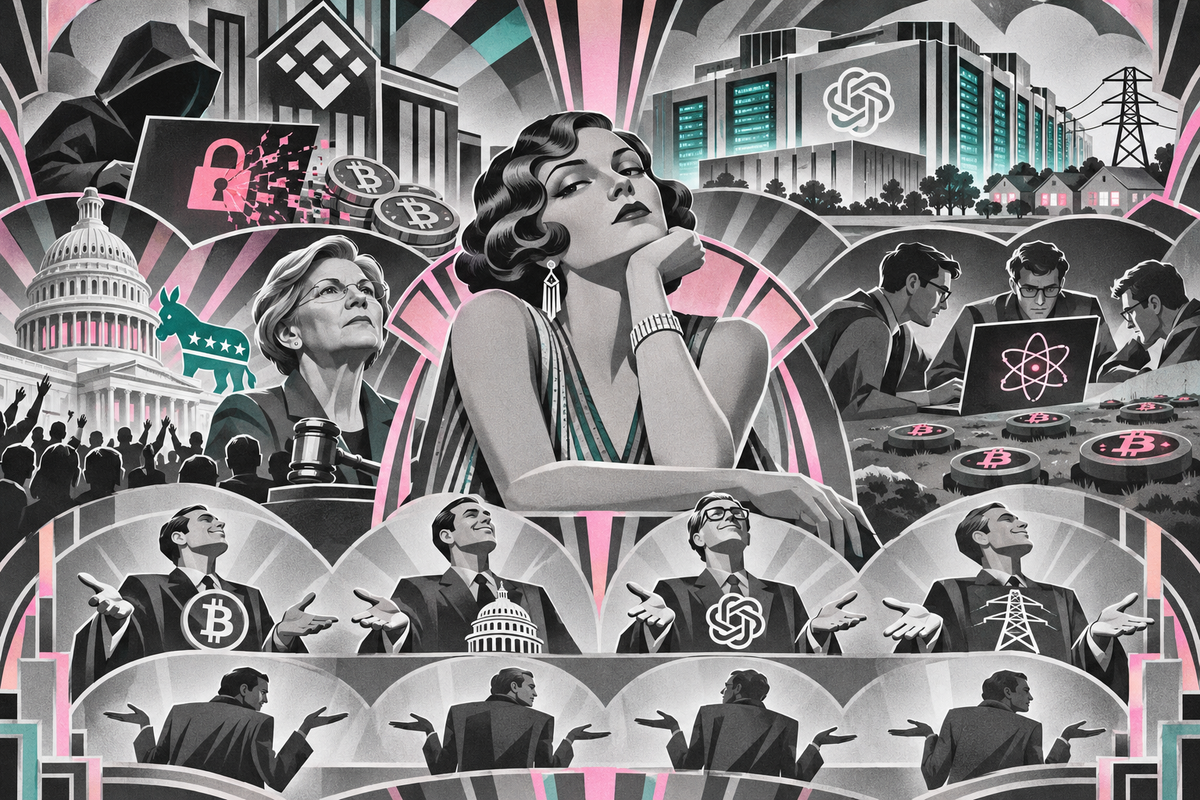
We started the week with Binance trying to recover from a $6.34 billion hack and ended it with OpenAI promising that its massive electricity-hungry data centers weren't going to cost the neighbors anything. Oh, and they're not even calling them data centers anymore. They're calling them compute campuses. Isn't that nice? Throw in a Democratic sweep of Congress, Elizabeth Warren potentially taking control of the Senate Banking Committee, and some Bitcoin developers talking about planting quantum landmines, and you've got yourself one hell of a week. But here's what struck me about all of it. Everybody wants you to trust them. The exchanges want you to trust them with your Bitcoin. The politicians want you to trust them with the rules. The AI companies want you to trust them with your electricity bill. And when something goes spectacularly wrong, everybody suddenly discovers that accountability is somebody else's department. It's getting ridiculous.
Your Keys, Their Problems, Your Money
Let's start with Binance because $6.34 billion is a number that deserves some attention. That's billion with a B, ladies and gentlemen. The largest cryptocurrency theft we've seen in dollar terms, and the original explanation involved a compromised developer's laptop. Now, that explanation became considerably more complicated as the investigation progressed, but think about that for a second. One of the largest cryptocurrency exchanges on the planet, handling billions upon billions of dollars in customer assets, suffers a catastrophic breach of its infrastructure. Binance reopened withdrawals, worked to replenish the stolen assets, and promised customers wouldn't bear the losses. Yay! Just wonderful. I'm glad they're trying to make everybody whole. But that doesn't make the underlying problem disappear. How did we build an entire industry around a technology designed to eliminate unnecessary trust and then convince everybody to hand their money right back to enormous centralized custodians?
Binance wasn't alone. Brazil's Mercado Bitcoin reported its own security incident. BTC Pay Server, one of my favorite open-source projects in Bitcoin, was warning operators about hot wallets being drained. Then there was the Liquid Network, which announced that its Bitcoin backing had finally been restored after a $320 million exploit two months earlier. Two months! And we've got people calling the attackers white hats even though hundreds of Bitcoin weren't immediately returned. Finding a security vulnerability and helping somebody repair it is valuable work. Keeping somebody else's Bitcoin without permission is something else entirely. We can call these things whatever we want, but changing the terminology doesn't change what happened. That's going to become something of a theme here.
South Korea's Gopax exchange suspended normal trading and withdrawals after reportedly receiving an email threatening a hack. An email. Now, I'm not saying Gopax was doing anything dishonest, and I don't know whether that threat was credible. Maybe the precaution was justified. But what kind of system are we building where somebody can threaten an exchange and thousands of customers suddenly have their normal access interrupted? What happens if another email arrives next Tuesday? Or Wednesday? Are we going to shut the whole thing down every time somebody gets creative with a keyboard? Again, customers have trusted somebody else to hold their assets, and somebody else gets to decide when those customers can use them. That's the issue. It's not that Bitcoin itself suddenly stopped working. It's the systems we build around it.
And yes, I know. Hardware wallets have had their own problems. I've talked about those problems extensively, particularly when manufacturers have made mistakes they should have caught long before their customers did. But that doesn't mean self-custody is dead. It means you have to pay attention to the tools you use. I still believe holding your own Bitcoin with properly designed, properly maintained hardware is one of the best options available. There's no magical device that eliminates every conceivable risk. There never was. But there's a big difference between accepting responsibility for your own keys and hoping some enormous exchange doesn't have another bad Thursday. We shouldn't confuse the security of Bitcoin with the security of every company that has figured out how to make money from it.
And here's the funny part. The Binance hackers have reportedly been converting stolen XRP and other tokens into Bitcoin. They're dumping the other stuff and moving into Bitcoin. Even the thieves apparently don't want to hold the garbage. Now, before somebody gets excited, theft is theft. I don't endorse stealing anybody's money. But you have to appreciate the irony. You've got this giant ecosystem of alternative cryptocurrencies promising to revolutionize everything, and when the criminals need somewhere to move the value, where do they go? Bitcoin. Of course they do. Just saying.
Washington Smells an Opportunity
Meanwhile, Washington looked at the whole cryptocurrency security mess and apparently decided what we needed was more Washington. CFTC Chairman Michael Selig used the Binance breach to argue for greater American oversight of offshore exchanges. An enormous exchange gets hacked, billions disappear, and the regulatory answer is essentially, "You know what would fix this? Give us more authority." Maybe some additional security standards would help. I'm not dismissing that possibility. But I would like somebody to explain precisely how bringing an overseas exchange under another American regulatory framework guarantees that the next developer's laptop, compromised signing system, or whatever the next disaster turns out to be won't result in another catastrophe. Regulation can establish responsibilities. It cannot magically make software secure. And I get a little suspicious when somebody starts treating an international crisis as the perfect advertisement for expanding their own jurisdiction.
Then came Tuesday's midterm elections. We went from Halloween to the Day of the Dead to Election Day, which seems appropriate considering some of the political characters we've been voting for over the years. Democrats swept both chambers of Congress. Everybody on one side celebrated. Everybody on the other side acted like the world was ending. And me? I'm looking at the same grocery bills, the same energy problems, the same war in Iran, and the same government that never seems to get any smaller regardless of who's holding the gavel. It's going to be more of the same, just with a different flavor. You can pull that voting lever with all the enthusiasm in the world, but don't expect your electricity bill to suddenly develop a conscience because somebody changed the color of Congress.
The cryptocurrency industry, however, has a genuine problem. The CLARITY Act as originally envisioned is not the CLARITY Act we're going to get, assuming we get one at all. Democrats are discussing stronger consumer protections, more SEC involvement, and ethics provisions aimed at public officials' cryptocurrency dealings. And Trump, through his family's meme coin and stablecoin ventures, has handed his opponents an enormous amount of ammunition. I don't care whether you like Trump or hate him. If a sitting president and his family are making money from businesses tied to an industry his administration regulates, that's a conflict-of-interest problem worth examining. I'd say exactly the same thing if Biden had done it. The cryptocurrency industry spent enormous amounts trying to influence Washington, but that doesn't mean Washington owes them the legislation they wanted.
Here's my prediction: Coinbase, Kraken, and the other big players are going to concede. They'll complain about excessive regulation. They'll talk about innovation. They'll tell us America is falling behind. And eventually they'll agree to rules they wouldn't have touched six months ago. Why? Because the alternative is sitting in regulatory limbo while somebody else agrees to play Washington's game and starts collecting the profits. These companies aren't going to abandon enormous revenues over some additional compliance requirements. They're going to accept the leash because they like making money too much not to. Bitcoin isn't going anywhere. But the institutions surrounding it are about to find out that political influence doesn't come with a lifetime warranty.
Same Old Game, New Names
And it's not just the United States. France rejected proposals to expand its exit tax to unrealized cryptocurrency gains, which was a rare moment of sanity, although I wouldn't start celebrating permanently. Greece approved a 10% cryptocurrency capital gains tax beginning in 2027. Governments everywhere are still trying to figure out how much of your financial activity they can monitor, tax, and control. Meanwhile, Australia raised interest rates as inflationary pressures persisted, and American employment figures had everybody guessing about what the Federal Reserve might do in December. People keep waiting for cheap money to come back and rescue everything. At some point, we're going to have to get over that. We have built an economy that seems to expect central banks to make everything painless, and then we act surprised when the bill arrives.
Which brings us to OpenAI. I have to admit, this may have been my favorite piece of corporate nonsense all week. Voters are getting increasingly irritated about AI data centers consuming electricity and water, and somebody apparently decided that part of the solution was to stop calling them data centers. Now they're compute campuses. Beautiful, innit?. Does changing the sign on the building reduce electricity consumption? Does it use less water? Does the transformer outside suddenly say, "Oh, thank goodness, it's a campus now," and start producing free power? Of course not. It's marketing. The really irritating part? This kind of thing works and works well. We let people change the language around a problem, and somehow the problem becomes more acceptable without necessarily changing at all.
OpenAI also announced a community compact promising that its future company-owned and operated facilities would pay their own electricity and infrastructure costs. Wonderful. Who enforces that? Where are the penalties? Who decides whether the numbers are accurate? And if the neighbors end up paying higher electricity rates anyway, does somebody reimburse them? I want to know exactly what happens when a company breaks one of these wonderful promises. Because a promise with no clearly established enforcement mechanism is not the same thing as protection. It's a statement. It's a press release. It's words on a website. And words are cheap, especially when you're trying to build enormously expensive infrastructure using resources that everybody else depends on.
Welcome to the Clown Show
Technology isn't making any of this simpler, either. We had a proposal for an Internet Court where AI agents could settle disputes using juries made up of other AI agents. We're heading toward a world where your AI agent negotiates with somebody else's AI agent, something goes wrong, and a third collection of AI agents gets to decide who's responsible. What could possibly go wrong? Imagine having your AI agent reserve a restaurant table, discovering that it agreed to some ridiculous cancellation terms, and then having an automated court inform you that you owe a hundred dollars because another machine decided the contract was valid. The opportunities for gaming these systems are extraordinary. We've opened the floodgates of stupid, and I suspect we're only beginning to see what comes floating through.
Bitcoin developers, meanwhile, are thinking about quantum landmines that could penalize future thieves trying to exploit vulnerable Bitcoin. It's a fascinating thought experiment, but the proposed collateral requirements could make ordinary transactions enormously complicated for people holding older coins. We're talking about potentially needing additional Bitcoin just to move the Bitcoin you already own. I understand the security argument. I understand the theoretical danger of quantum computing. But humans don't like jumping through fifty-seven hoops to accomplish something that ought to be simple. At some point, the complexity becomes its own problem. We keep inventing more elaborate ways to secure money, more complicated ways to regulate money, and more sophisticated systems for deciding who gets access to money. And I find myself wondering whether we've made the whole thing unnecessarily difficult.
That's what I keep coming back to after this week. Bitcoin gives us an opportunity to take personal responsibility for our money without asking a bank, an exchange, or a government for permission. That's an extraordinary thing. But it doesn't eliminate the need to think, to learn, or to take responsibility for our own decisions. The larger world seems determined to move in the opposite direction, building more layers of institutions, algorithms, promises, and regulations between people and the things they actually own. Maybe some of those layers will prove useful. Maybe some will keep people safer. But I don't believe we should automatically trust them just because somebody in a suit, or somebody running a giant technology company, tells us everything is under control.
Because after a week like this, I think it's a perfectly reasonable question to ask: Whose control?
Episodes Covered:




- Bitcoin weekly news November 2026
- Binance $6.34 billion hack
- CLARITY Act and Democratic Congress
- Bitcoin self custody and exchange security
- OpenAI data centers and electricity costs
Member discussion: